
Start with the reporting date, accounts or projects included, and the person who approves exceptions. This accounts receivable aging review should explain its scope before anyone changes a record.
Accounts receivable aging review
Separate collectible invoices, documented disputes, unapplied cash, and owner decisions.
Published · 8 minute read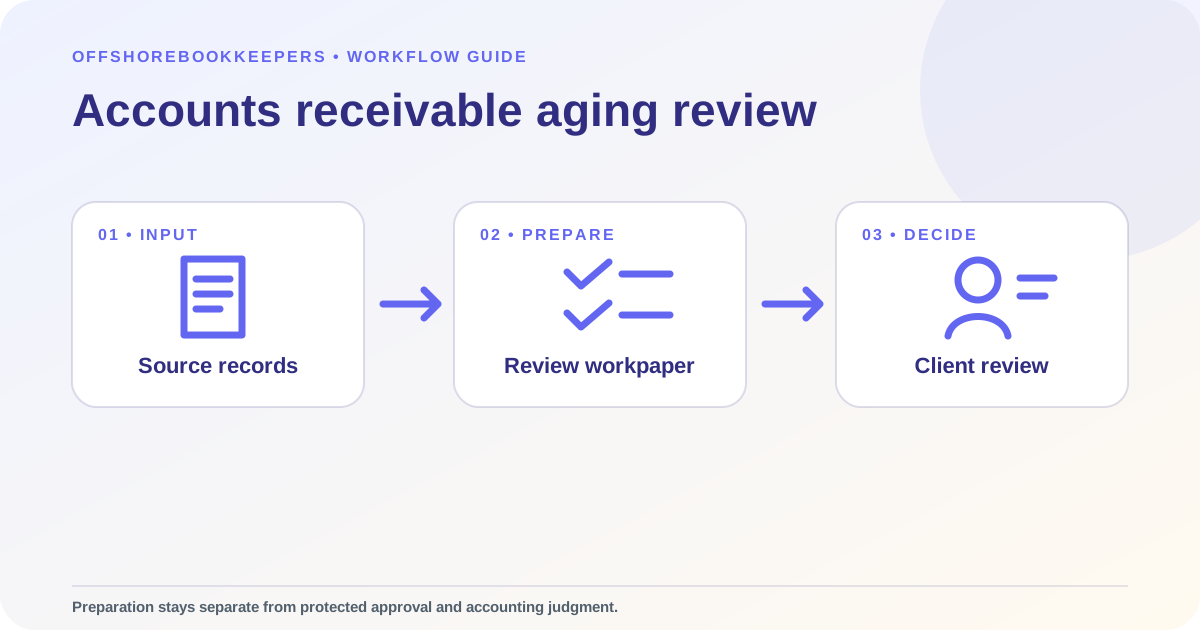
The short answer
- Separate collectible invoices, documented disputes, unapplied cash, and owner decisions.
- Keep source evidence, reconciliation detail, and unresolved questions together.
- Leave approval, policy, and accounting judgment with the named finance owner.
Define the review boundary
Build the evidence packet
Collect customer, invoice, due date, balance, last action, and dispute status. Preserve the original source and give each unresolved item a named owner and due date. A bookkeeper can prepare the detail and document questions without making a policy or accounting judgment.
Reconcile before presenting
Tie the aging total to the receivables control account, then test invoices, unapplied receipts, credits, and disputed balances by customer. Keep cutoff differences visible and document the source for any proposed reallocation instead of changing aging buckets to make the totals agree.
Keep approval independent
The bookkeeper may refresh aging, attach collection notes, and identify stale items. Credit holds, payment plans, write-offs, refunds, and changes to collection policy require the designated credit or finance owner; the preparer should not approve their own adjustment.
Close with a useful handoff
The final packet should show the period, source reports, reconciled totals, open exceptions, reviewer decision, and next review date. That structure makes accounts receivable aging review useful for owners and finance managers who need dependable books without losing control.