
Start with the reporting date, accounts or projects included, and the person who approves exceptions. This cash application for unapplied receipts should explain its scope before anyone changes a record.
Cash application for unapplied receipts
Link receipts to customer accounts while keeping uncertain matches on hold.
Published · 8 minute read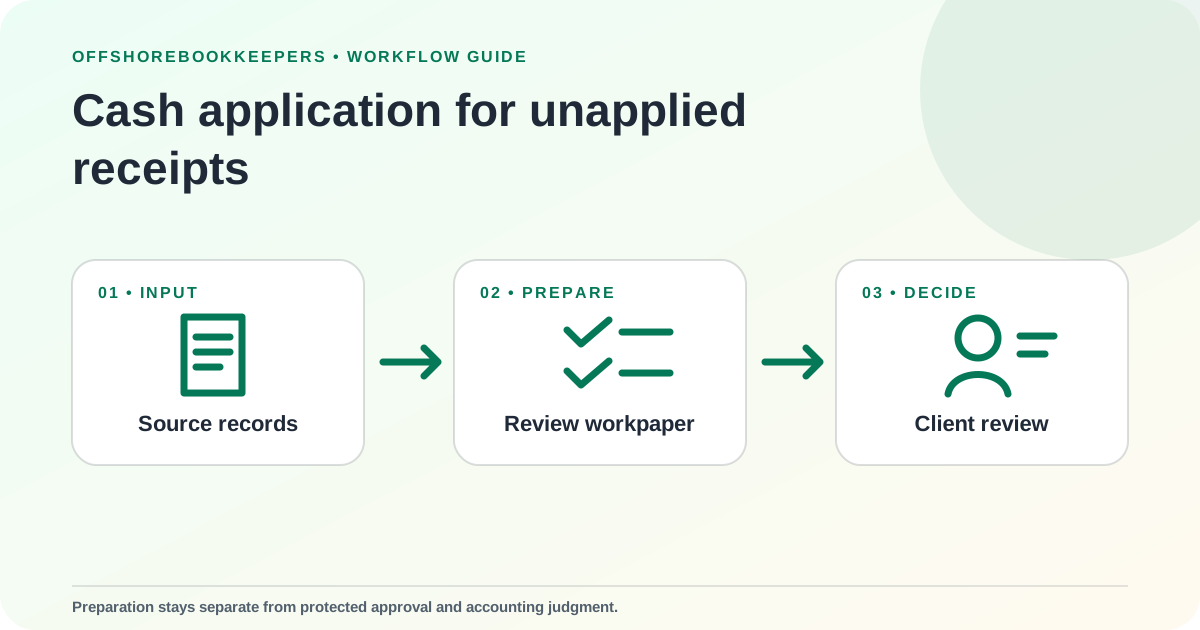
The short answer
- Link receipts to customer accounts while keeping uncertain matches on hold.
- Keep source evidence, reconciliation detail, and unresolved questions together.
- Leave approval, policy, and accounting judgment with the named finance owner.
Define the review boundary
Build the evidence packet
Collect remittance, amount, date, customer history, and deposit reference. Preserve the original source and give each unresolved item a named owner and due date. A bookkeeper can prepare the detail and document questions without making a policy or accounting judgment.
Reconcile before presenting
Reconcile the unapplied-cash register to bank deposits, processor settlements, and the customer subledger. For each receipt, retain candidate invoices, remittance evidence, currency, short-pay detail, and prior applications so a forced match cannot conceal an overpayment or duplicate posting.
Keep approval independent
Support staff can research payers and propose invoice matches, while the receivables owner authorizes cross-customer transfers, refunds, credits, write-offs, and unidentified-cash treatment. Any manual application should retain separate preparer and reviewer identities.
Close with a useful handoff
The final packet should show the period, source reports, reconciled totals, open exceptions, reviewer decision, and next review date. That structure makes cash application for unapplied receipts useful for owners and finance managers who need dependable books without losing control.