
Start with the reporting date, accounts or projects included, and the person who approves exceptions. This inventory shrinkage reconciliation should explain its scope before anyone changes a record.
Inventory shrinkage reconciliation
Compare count results, movement records, and the ledger before an adjustment.
Published · 8 minute read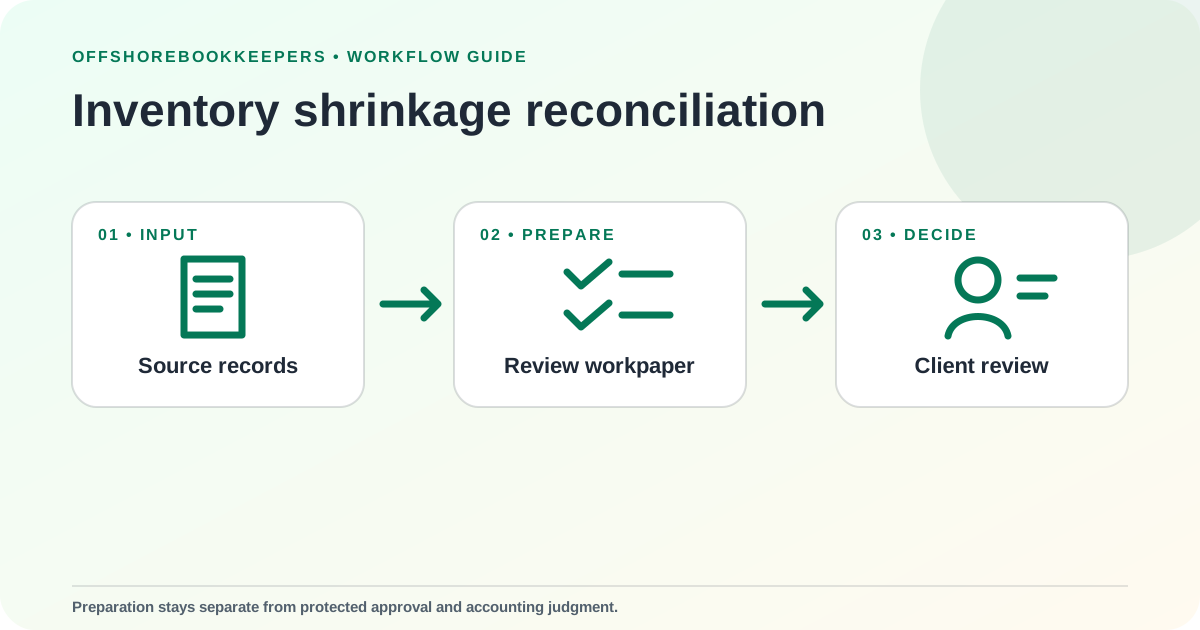
The short answer
- Compare count results, movement records, and the ledger before an adjustment.
- Keep source evidence, reconciliation detail, and unresolved questions together.
- Leave approval, policy, and accounting judgment with the named finance owner.
Define the review boundary
Build the evidence packet
Collect count date, location, quantity, movement, damage, and variance evidence. Preserve the original source and give each unresolved item a named owner and due date. A bookkeeper can prepare the detail and document questions without making a policy or accounting judgment.
Reconcile before presenting
Bridge book quantity to the approved physical count by SKU and location, preserving count sheets, movements during the count window, units of measure, and costing data. Separate timing and master-data errors from unexplained quantity loss before calculating a proposed adjustment.
Keep approval independent
Bookkeeping support may compile count variances and trace receiving or shipment records. Operations validates physical causes, and authorized finance leadership approves shrinkage thresholds, reserve or write-off treatment, and inventory entries independently of the counter and preparer.
Close with a useful handoff
The final packet should show the period, source reports, reconciled totals, open exceptions, reviewer decision, and next review date. That structure makes inventory shrinkage reconciliation useful for owners and finance managers who need dependable books without losing control.