
Start with the reporting date, accounts or projects included, and the person who approves exceptions. This month-end accrual review should explain its scope before anyone changes a record.
Month-end accrual review
Identify services received but not billed and document the basis and reversal plan.
Published · 8 minute read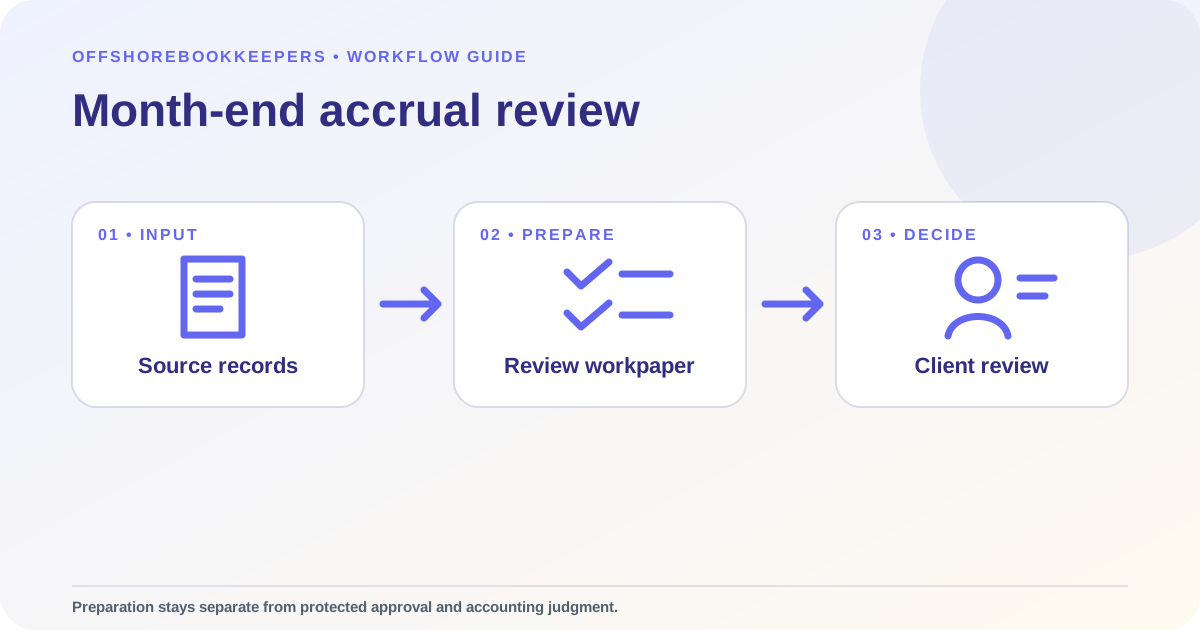
The short answer
- Identify services received but not billed and document the basis and reversal plan.
- Keep source evidence, reconciliation detail, and unresolved questions together.
- Leave approval, policy, and accounting judgment with the named finance owner.
Define the review boundary
Build the evidence packet
Collect cutoff, purchase orders, receiving records, contracts, prior accruals, and later invoices. Preserve the original source and give each unresolved item a named owner and due date. A bookkeeper can prepare the detail and document questions without making a policy or accounting judgment.
Reconcile before presenting
Roll forward each accrual from the prior estimate through reversal, invoice receipt, current estimate, and ending balance. Compare purchase activity and subsequent invoices, and retain quantity, service-period, rate, and source evidence for every proposed amount or release.
Keep approval independent
The preparer may gather evidence, update formulas, and draft entries under an approved method. Budget owners confirm goods or services received, while the controller or CPA approves estimates, thresholds, releases, classification, and any policy departure.
Close with a useful handoff
The final packet should show the period, source reports, reconciled totals, open exceptions, reviewer decision, and next review date. That structure makes month-end accrual review useful for owners and finance managers who need dependable books without losing control.