
What evidence shows that a bookkeeping function can continue when its usual preparer is unavailable? This report examines continuity at the level of records, access, responsibilities, and review.
Access & Governance
Continuity evidence for an outsourced bookkeeping function
Research on backup coverage, recoverable records, and role continuity when bookkeeping support depends on a distributed team.
Published · 4 listed sources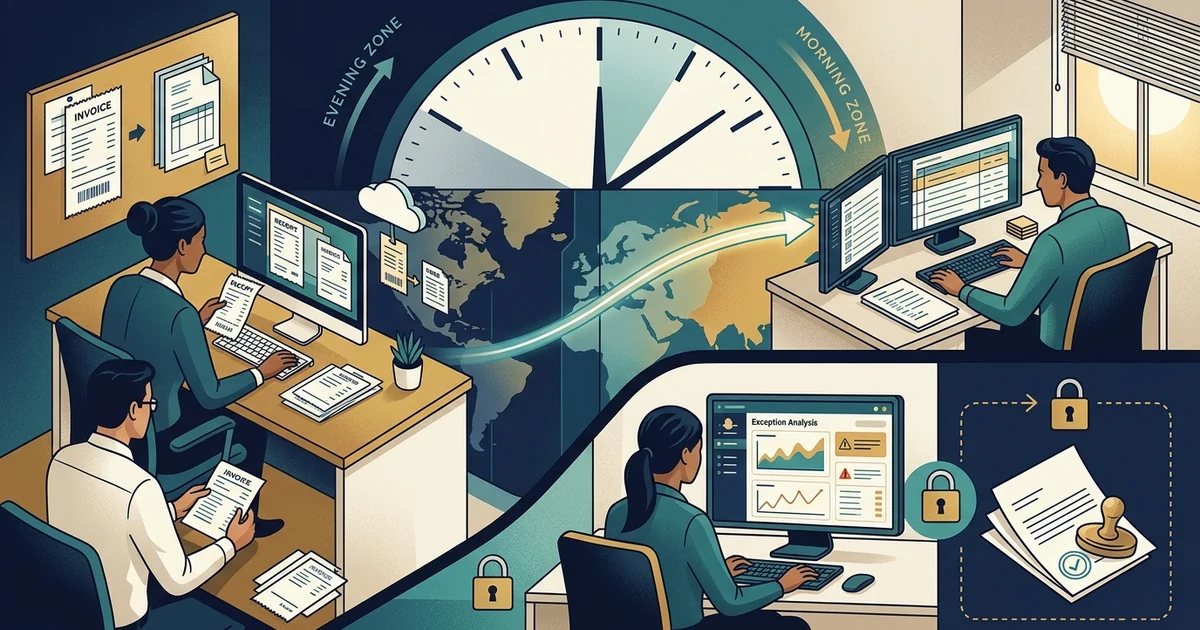
Key takeaways
- Continuity is demonstrated by a tested handoff, not a promise of availability.
- Critical records need recoverability and an identified alternate owner.
- The test should include access, evidence, and review decisions.
Research question
Methodology
NIST contingency and access guidance provides the continuity and permission frame. GAO addresses internal-control responsibility, and IRS guidance supplies recordkeeping context. The proposed test selects a representative open transaction, current reconciliation, and close task. A substitute must locate the records, obtain authorized access, understand the status, complete or escalate the task, and leave review evidence.
Findings
Continuity fails in different ways. A backup may have instructions but not the source documents. The files may exist but the alternate lacks access. Access may work while the status history is missing. A team may resume preparation while the reviewer remains unknown. These are separate findings and should not be collapsed into “coverage available.”
Relevance to outsourced bookkeeping
The client should retain ownership of the system of record and maintain a current list of open exceptions, close dates, and review owners. A support provider can document task context and prepare a handoff, but continuity does not mean transferring payment authority or accounting judgment to an unreviewed substitute. Test after system changes and meaningful role changes, not only after an incident.
Limitations and conclusion
Public guidance does not establish a required test frequency for every small business, and a tabletop exercise does not prove recovery under every disruption. The evidence supports a limited conclusion: continuity is credible when a representative bookkeeping task can be handed to an authorized alternate with records, access, and review evidence intact. The test result should state what it did not cover.
Source notes
This report addresses operational continuity. It does not provide disaster-recovery engineering or legal retention advice.
Evidence map
These notes connect bounded statements on this page to the listed public sources. They do not turn operational interpretations into empirical findings.
- The source list includes NIST, Contingency Planning Guide as public guidance relevant to hiring controls.
- NIST SP 800-53 Rev. 5 is listed to frame review questions about continuity evidence for an outsourced bookkeeping function.
- U.S. GAO, Standards for Internal Control provides context; this report does not treat that source as proof that a staffing model causes an outcome.