Bookkeeping Operations

Source-version control in outsourced bookkeeping: when is evidence current?

Research on preserving current and superseded source versions so remote bookkeeping preparation does not rely on an unmarked document copy.

Research on preserving current and superseded source versions so remote bookkeeping preparation does not rely on an unmarked document copy.

Key takeaways

  • Currentness requires a defined business event, effective date, owner, and supersession rule.
  • Retaining old versions improves reconstruction only when the active version is unambiguous.
  • A source-control test should include amended, duplicated, and withdrawn records.

Current is a relationship, not a file property

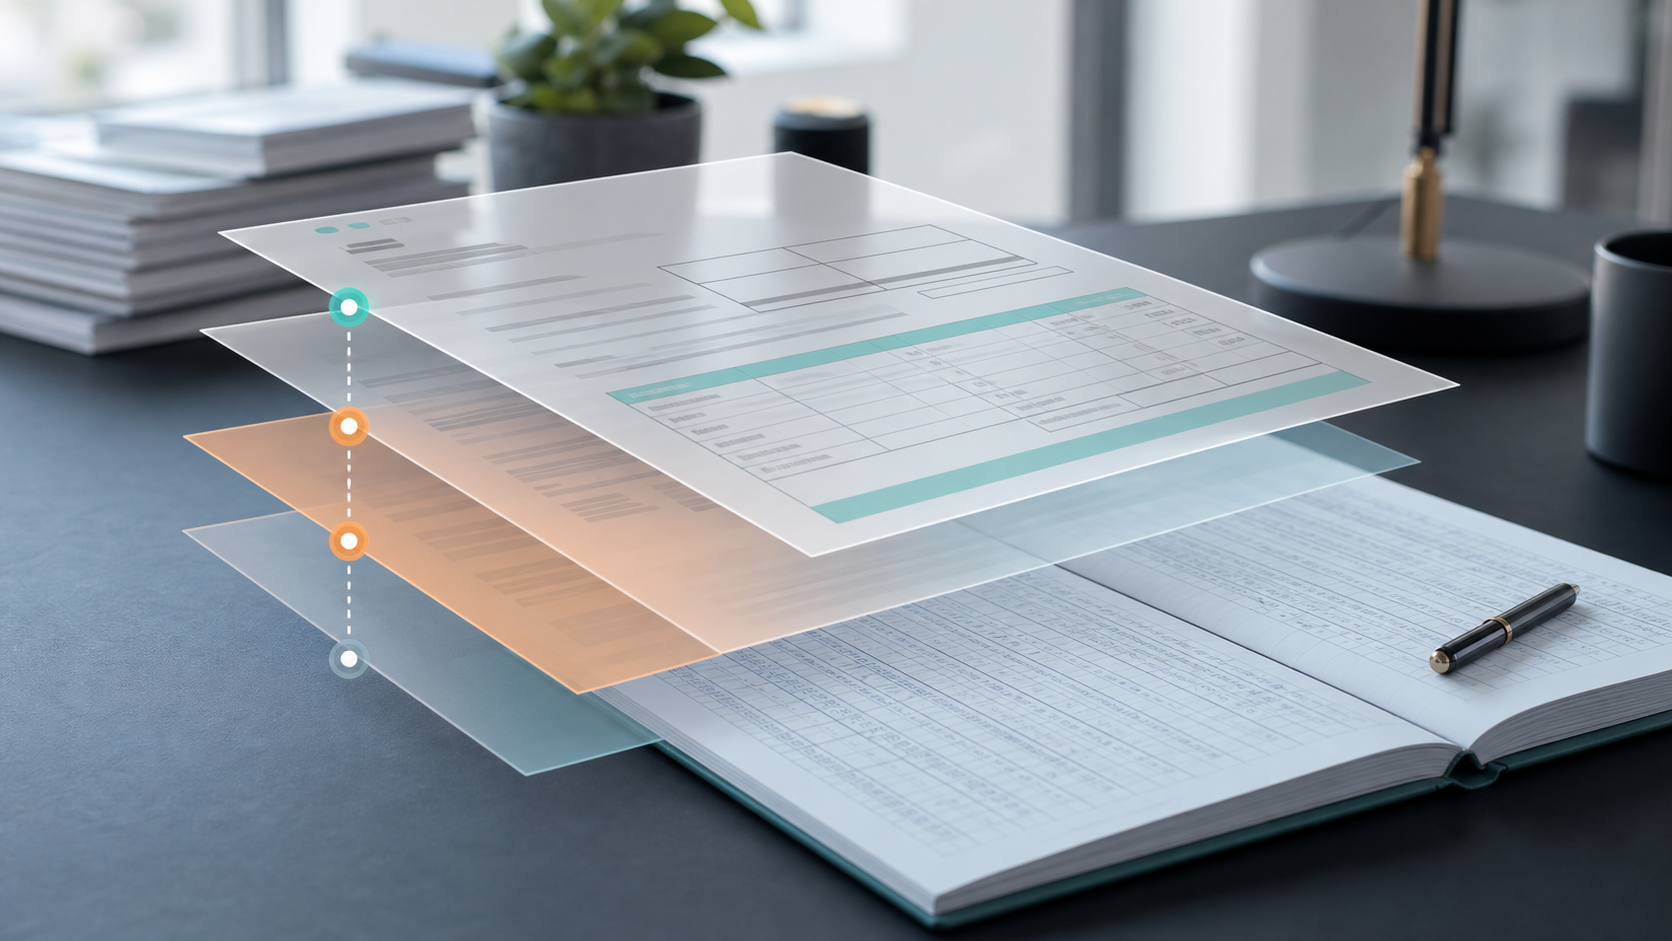
A PDF or spreadsheet does not announce that it is the right version for a ledger period. Currentness depends on the business event, effective date, source owner, and the rule for replacing an earlier record. A vendor form may be amended after a payment request. A payroll register may be rerun. A bank statement may be corrected or reissued. A client schedule may carry a new tab while the filename stays the same.

The research question is therefore about version relationships. Can a reviewer identify the active source, see what it superseded, understand who supplied it, and connect the selected version to the bookkeeping action? That is particularly important when an offshore preparer receives documents asynchronously and cannot rely on an informal desk conversation.

The source-version ledger

An operating source ledger can be lightweight. Record a stable item key, source type, period, received time, effective time if known, version or revision marker, owner, status, superseded item, and linked bookkeeping work. Status should distinguish received, accepted for preparation, replaced, withdrawn, and under clarification. A replacement should not erase the previous record; it should explain the relationship and identify the new active version.

A practical naming convention can help, but the convention is not the control by itself. The important test is whether a person who did not receive the original message can identify the governing source and reconstruct the change. Keep the source owner’s statement of intent when it is relevant, and do not infer intent from a filename, upload order, or a document that happens to have a newer creation date. Those distinctions reduce the risk that an offshore preparer treats system metadata as a substitute for client confirmation.

The aim is not bureaucratic metadata. It is to prevent three common failures: posting from the first document rather than the governing one, reopening a closed question with a different copy, and treating a retained historical version as active. GAO and COSO support documentation, responsibility, communication, and monitoring. ISO 15489 and IRS material provide records context. NIST and CISA support integrity, access, and event-history thinking.

Testing amended and conflicting sources

Test four cases rather than only a clean handoff. In the first, the client sends a clear replacement before posting. In the second, the replacement arrives after preparation but before review. In the third, two copies have conflicting totals or dates. In the fourth, the source owner withdraws a document after the entry is posted. The reviewer should identify the active version, trace the decision, and state who must resolve the conflict.

If a preparer can change a source label without preserving the prior state, the test exposes a control weakness. If the team retains every copy but cannot identify the active one, storage has increased without increasing reliability. If the reviewer finds the change but not the reason, the correction is not fully explainable. Each result should be assigned to a source-owner, access, procedure, or review problem.

The test should be repeated across the main source types used by the bookkeeping operation rather than on one document family alone. A payroll register, bank statement, vendor form, and management schedule can each have different owners and revision behavior. Comparing them reveals whether the rule is truly general or merely works for a single file format. It also helps the client decide which evidence belongs in the bookkeeping workpaper and which remains in the authoritative source system.

Role boundaries in a remote bookkeeping model

The preparer can capture source metadata, link the approved version, compare fields, and stop when versions conflict. The reviewer can check that the selected source is current under the agreed rule and can ask for clarification. The client-side owner decides whether a replacement changes an accounting conclusion, approval, contract interpretation, tax position, or reporting treatment. A system administrator controls access and retention settings. Keeping those roles visible matters more than naming a particular platform.

Methodology and limitations

This qualitative review covered ten public sources on records management, control, data integrity, access, logging, and evidence. Sources were chosen for authoritative guidance and mapped to currentness, supersession, responsibility, and reconstruction. No private source library, software audit, client interview, or failure-rate study was used. The source ledger is a proposed operating interpretation, not a records-management certification or a guarantee of audit acceptance.

The evidence does not establish one retention period, naming convention, permission model, or version-number format for every organization. It also cannot tell a team whether a replacement changes the correct accounting treatment. Local obligations, contracts, system limits, and client policy matter. Readers should test with redacted examples and have accountable owners approve the rule before applying it to live bookkeeping work.

Evidence-led conclusion

The evidence supports treating currentness as an explicit relationship among source, effective event, owner, and supersession history. For an outsourced bookkeeping team, that makes preparation more reviewable and makes later reconstruction less dependent on memory. Retention alone is insufficient; the active version and the reason for change must be clear. OffshoreBookkeepers.com readers should test amended, conflicting, and withdrawn records, and escalate policy implications rather than asking a remote preparer to resolve them.

Sources

Listed sources

  1. U.S. GAO, Standards for Internal Control
  2. COSO, Internal Control Framework
  3. ISO, ISO 15489 Records Management
  4. NIST, Cybersecurity Framework 2.0
  5. NIST, Data Integrity
  6. CISA, Identity and Access Management
  7. IRS, Recordkeeping
  8. PCAOB, AS 1105 Audit Evidence
  9. AICPA, Audit Evidence
  10. CISA, Logging Made Easy

Related research