Bookkeeping Operations

A protocol for tracking account-mapping changes

How to define, count, and review account-mapping revisions without mistaking change volume for control quality.

How to define, count, and review account-mapping revisions without mistaking change volume for control quality.

Key takeaways

  • Count an approved mapping-rule revision as the event; report affected transaction rows as a separate measure.
  • Retain the prior value, new value, effective date, reason, approver, and mapping version for every event.
  • Do not interpret a high or low change count without checking migrations, new products, chart-of-accounts revisions, and missing change records.

The event to count

Choose one source-to-ledger mapping process and a fixed run of accounting periods. Define an event as a separately approved revision that changes where a source value is posted. Record the source field or value, previous destination, new destination, effective date, requestor, approver, reason, and mapping version. Formatting edits and reruns that leave the rule unchanged are not events.

A bulk upload is one event only when a single approval covers the whole set. If individual rules were separately requested or approved, each is an event. Freeze that convention before extracting results. The protocol adapts NIST's configuration-change concepts to bookkeeping rules; NIST does not establish a bookkeeping change-frequency benchmark.

Preserve lineage before calculating a rate

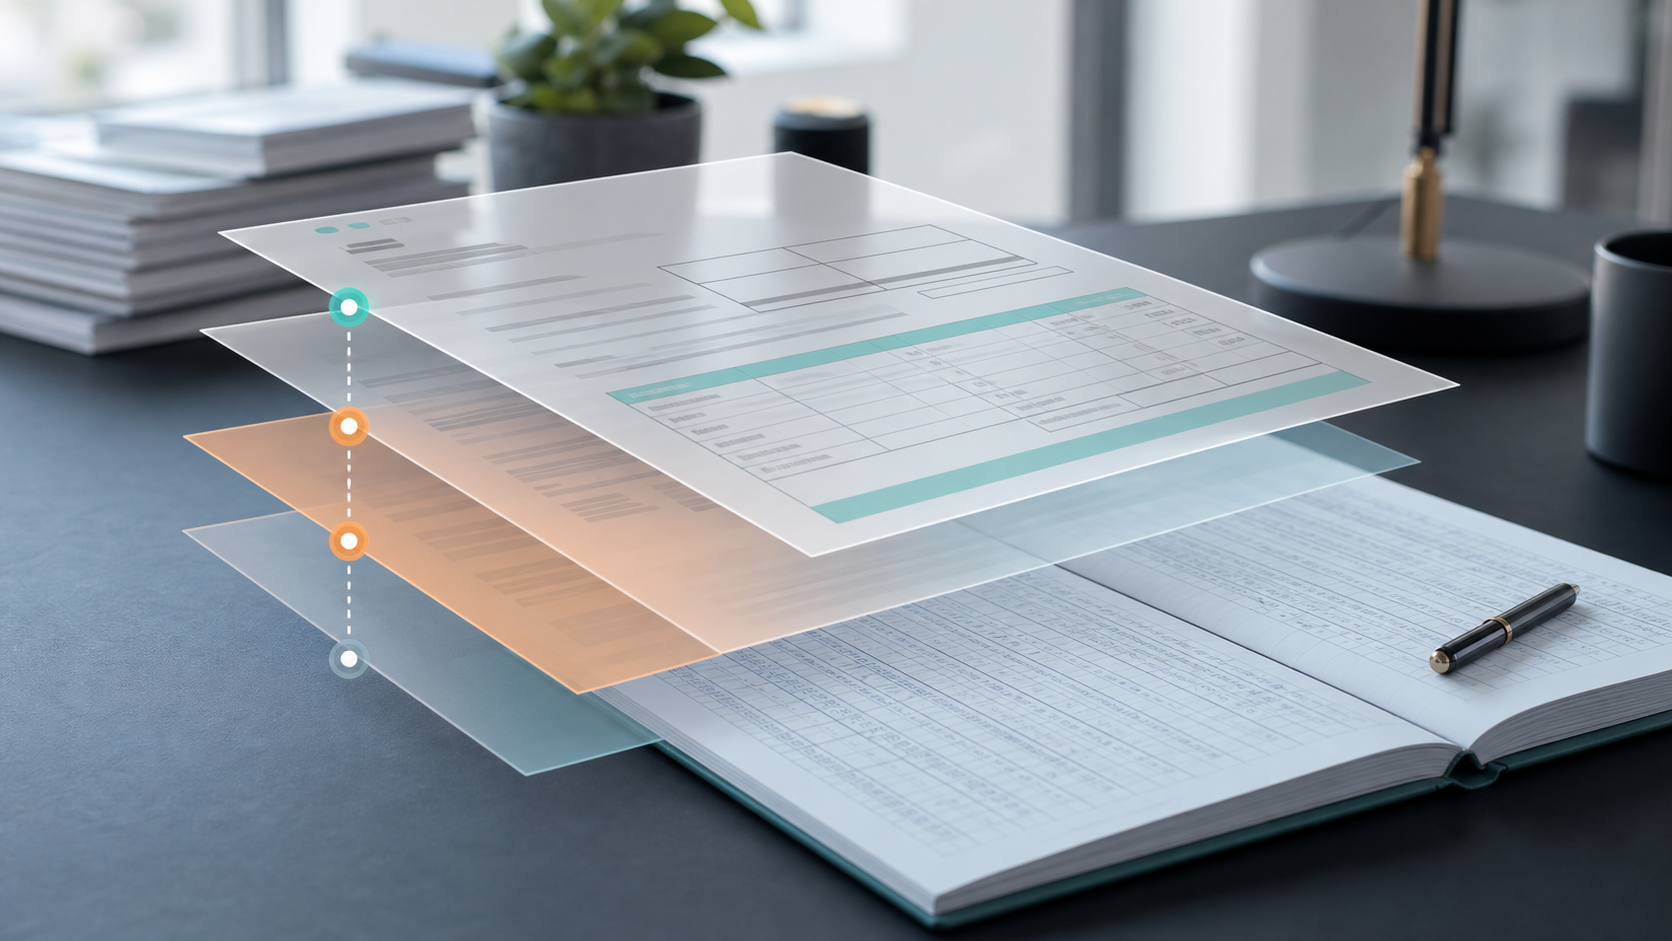
Keep the opening mapping table, every in-scope change record, and the closing version. Those three layers allow a reviewer to reconstruct what was effective at a given time. GAO's Green Book provides the general control basis for assigned responsibility and documented performance, while PCAOB AS 1215 supplies an audit-context example of attributable preparation, review, and later changes. Neither source determines which ledger account is correct.

Extract mapping metadata rather than transaction narratives or personal data. A reviewer should trace a sample from the opening rule through the approval and into the closing version, including reversals and bulk uploads. Any rule visible in the closing table but absent from the change log belongs in an exception queue, not in a silently repaired dataset.

Two measures, two denominators

First, report the count of approved revision events by period. Second, report the proportion of opening in-scope rules changed at least once. The second measure uses the frozen opening rule population as its denominator; rules introduced during the period should be reported separately. A later reversal is another event because erasing the original would hide sequence.

Also report the number of transaction rows affected by each revision. That is an exposure measure, not another way to count changes: one approved rule revision may touch one row or thousands. Preserve the calculation version, exclusion table, and treatment of missing approvals so another reviewer can reproduce the summary.

Interpret the pattern, not just the count

A migration, new sales channel, product launch, acquisition, or approved chart-of-accounts redesign may produce a concentrated cluster of valid revisions. A quiet period may indicate stable rules, but it may also reflect incomplete tickets or spreadsheet overrides outside the controlled workflow. Annotate those conditions before comparing periods.

The count cannot establish mapping accuracy, control effectiveness, or the cause of a downstream correction. Those questions require inspection of the underlying accounting decision, approval evidence, and affected postings. No mapping population was analyzed for this article, so it supplies no external target or industry norm.

Ownership and reporting limits

A bookkeeper may assemble versions, link approvals, and calculate the declared measures. The finance or system owner should approve the population, effective-date rule, and bulk-change convention. A reviewer should test lineage and escalate unapproved or unexplained changes. The measurement exercise must not itself authorize a new accounting treatment.

Systems differ in rule granularity, inheritance, deletion history, and versioning. Published results should therefore identify the system, periods, event definition, opening denominator, missing-history limitations, bulk-change treatment, and material migrations. Comparisons are meaningful only when those design choices are compatible.

Evidence map

These notes connect bounded statements on this page to the listed public sources. They do not turn operational interpretations into empirical findings.

  1. NIST SP 800-53 Rev. 5, Update 1 control CM-3 describes reviewing, approving, documenting, and retaining records of configuration-controlled changes. Treating a bookkeeping mapping rule as a configuration item is this brief's operational analogy, not a NIST requirement for bookkeeping.
  2. GAO-14-704G Principles 10 and 12 address designing control activities and deploying them through policies that define responsibility and document performance. Those principles support the proposed approval record; GAO does not prescribe a mapping-change metric.
  3. PCAOB AS 1215 uses preparer, reviewer, date, and post-completion change records in an audit-documentation context. This brief borrows those traceability attributes for a mapping log and does not claim that AS 1215 governs ordinary bookkeeping.

Listed sources

  1. NIST SP 800-53 Rev. 5, Update 1
  2. U.S. GAO, Standards for Internal Control in the Federal Government (GAO-14-704G)
  3. PCAOB AS 1215, Audit Documentation

Related research