
This study defines a protocol for tracing cloud-marketplace activity through disbursement and cash. It reports no private marketplace data or benchmark and does not provide accounting, tax, legal, security, or investment advice.
Industry Workflows
Cloud-marketplace disbursements: research design for a reproducible payout bridge
A controlled study of how cloud marketplace usage, customer charges, credits, fees, taxes, holds, foreign exchange, disbursements, and ledger entries connect.
Published · 5 listed sources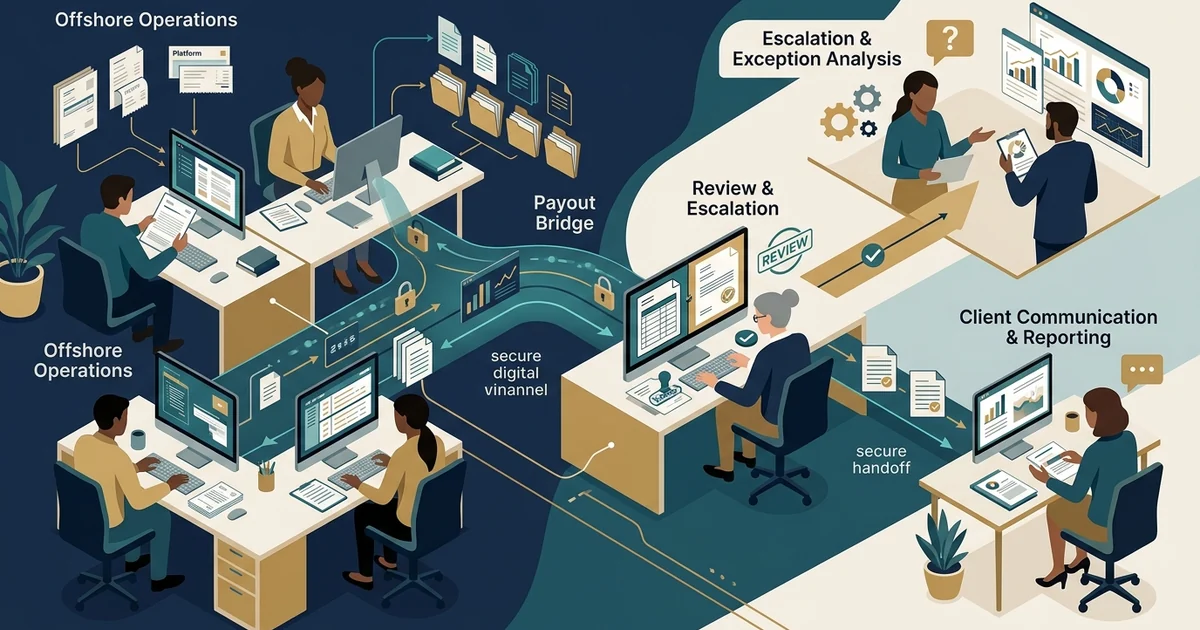
Key takeaways
- Preserve marketplace-native identifiers across usage, billing, earnings, and payout files.
- Explain every gross-to-net component instead of reconciling only the deposit.
- Keep revenue, tax, contract, reserve, and write-off judgments with qualified client owners.
Scope and decision boundary
Why a payout is a chain, not a transaction
A software seller using a cloud marketplace may observe customer usage, a customer charge, a platform invoice, reported earnings, a scheduled disbursement, and a bank receipt at different times. Private offers, annual commitments, metered usage, refunds, credits, taxes, marketplace fees, withholding, reserves, and currency conversion can alter the path. Matching a payout total to cash proves neither the completeness of billable activity nor the accuracy of every deduction.
Model the flow as linked events. Preserve offer identifier, agreement or private-offer identifier, customer account token, product and dimension, usage period, invoice identifier, transaction identifier, earning identifier, payout identifier, currency, legal entity, and source report. Keep original identifiers even when a normalized key is created. Amount-and-date matching is a last-resort candidate method, not proof.
The research question is whether an eligible source population can be traced through marketplace reports to ledger balances and cash, with unexplained transitions visible. It does not decide whether the seller is principal or agent, when revenue is recognized, who bears tax obligations, or whether a contractual deduction is enforceable.
Report inventory and extraction controls
Build a platform-specific report inventory before writing transformations. For each report record its purpose, grain, available history, refresh behavior, time zone, currency convention, identifier fields, sign convention, and whether prior rows can change. Official vendor documentation helps interpret fields, but the saved report version is the evidence for a period.
Freeze usage, billing, transaction, earnings, disbursement, tax, refund, and adjustment reports. Record seller account, filters, extraction timestamp, row count, control totals, and file hash. Save portal screenshots only as secondary context; structured exports are preferable for recomputation. If an API is used, retain endpoint version, request parameters, pagination counts, and response checksum without storing credentials.
Test report coverage dates and duplicates. A file named for September may include corrections from August or exclude late September usage. Assign source event dates separately: usage start and end, customer invoice, marketplace transaction, earning, payout initiation, bank value, and ledger posting. Do not collapse them into one “date.”
Usage-to-billing completeness
Start from the seller-controlled usage or entitlement population when available. Aggregate only at a grain compatible with the marketplace report, preserving product dimension, customer, agreement, and period. Compare eligible units with marketplace-reported units. Classify differences as timing, threshold or rounding, rejected meter record, duplicate, cancelled entitlement, free tier, contract exception, missing identifier, or unexplained.
Where the marketplace is the only source of customer activity, disclose that independence is limited. Recalculation can still test internal consistency, but it cannot establish that the platform captured all real-world usage. For private offers, compare the effective offer version and term with the billing period. Escalate ambiguity about amendments and renewals instead of selecting the rate that removes a difference.
Retain zero-value and negative lines. They may represent free entitlements, credits, reversals, or corrections. Removing them before reconciliation can make activity coverage appear complete. Track late-arriving usage by originating cohort so a later correction is not mistaken for current-period growth.
Earnings and payout bridge
For every payout, bridge customer charges or other approved gross base to seller earnings: gross activity, less customer credits and refunds, less marketplace fees, plus or minus taxes and withholding under the platform's presentation, less holds or reserves, plus released holds and prior-period adjustments, equals payable amount. Then bridge payable amount to disbursed and bank-received cash.
Each component needs a report field, documented mapping, and ledger destination. “Marketplace adjustment” is not sufficiently specific. Preserve adjustment code, originating transaction, stated reason, source period, and owner. Reperform fee calculations for selected transactions using the effective marketplace terms supplied and approved by the client. Contract interpretation stays outside the bookkeeping role.
Separate currencies throughout. Record transaction, settlement, and bank currencies; platform exchange rate; conversion timestamp; fee currency; and bank charges. Reconcile foreign-exchange differences rather than burying them in marketplace fees. Management approves the rate source and accounting treatment.
Build a clearing roll-forward by platform, seller account, legal entity, and currency. Opening marketplace receivable, plus current eligible earnings and approved adjustments, less payouts, refunds or other settled components, equals closing receivable. Tie it to the ledger and to the open earning population. Investigate negative balances, old holds, and cash posted without payout identifiers individually.
Cohorts, exceptions, and interpretation
Analyze the time from usage to billing, billing to earning, earning to payout eligibility, initiation to bank receipt, and receipt to ledger posting. Use cohorts by originating event rather than combining all clocks. Publish medians, useful percentiles or bands, counts, values, and oldest open items. A single average masks the right tail.
An exception register should distinguish rejected usage, missing agreement mapping, unmatched transaction, unsupported fee, refund awaiting source, tax field needing qualified review, held earning, failed payout, bank difference, duplicate ledger entry, and late correction. Give each state an evidence requirement, owner, due date, and escalation path. Reopened cases remain visible.
Segment results by platform, account, offer type, billing model, product dimension, currency, geography when appropriate, and exception reason. Variation is descriptive. Product mix, customer terms, platform calendars, report refreshes, and currency settlement can explain differences. Do not infer employee performance or marketplace misconduct from an uncontrolled comparison.
Role design and independent review
An offshore bookkeeper can download approved reports, verify control totals, maintain mappings, prepare bridges, post client-approved entries, and assemble exceptions. Client finance retains revenue policy, estimates, principal-agent conclusions, tax treatment, contract disputes, journal approval, reserve and write-off decisions, and period lock. Platform administrators retain access provisioning and credential recovery.
Use named accounts, multifactor authentication, least privilege, and approved storage. Seller reports can reveal customer and commercial terms. Minimize fields passed into working files. A handoff should state the exact extraction cutoff, file versions, processed payouts, unresolved blockers, and decisions needed during overlap hours.
The reviewer traces samples forward from usage and backward from payouts, recomputes selected fees, inspects offer changes around effective dates, tests currency bridges, and reviews all material manual entries, holds, refunds, negative earnings, and unmatched cash. Confirm population row counts before sampling and verify that preparers did not approve their own exceptions.
Limits and required archive
Marketplace reports can be revised, identifiers can change after migrations, platform documentation can evolve, and customer disputes may resolve after cutoff. Seller-controlled usage may not be independent of billing logic. A reconciliation therefore supports a bounded period and declared data set; it does not prove future collections, control effectiveness, or universal platform accuracy.
Archive source exports and parameters, report dictionary, identifier crosswalk, offer-version map, usage comparison, payout bridges, clearing roll-forward, currency schedule, exception register, review selections, approvals, and correction history. The conclusion should quantify covered and missing populations and identify unresolved judgment. A reproducible bridge is more useful than a cash tie-out whose gross activity and deductions cannot be reconstructed.
Run a revision analysis before archiving. Re-extract a prior closed reporting window through the same approved method and compare row keys, status, amounts, and timestamps with the frozen original. Classify additions, deletions, and modifications by the platform's documented behavior where possible. Do not replace the original close file. The comparison measures report mutability and informs the next review cadence; it does not prove that either version is wrong. Where changes affect posted periods, route a quantified, evidence-linked correction proposal to the authorized accounting owner.
Sources and checked dates
- AWS Marketplace Seller Reports - Amazon Web Services; checked October 2, 2026.
- Microsoft commercial marketplace payout policy - Microsoft; checked October 2, 2026.
- PCAOB AS 1105 - PCAOB; checked October 2, 2026.
- IRS Publication 583 - IRS; checked October 2, 2026.
- NIST Cybersecurity Framework 2.0 - NIST; checked October 2, 2026.
Evidence map
These notes connect bounded statements on this page to the listed public sources. They do not turn operational interpretations into empirical findings.
- AWS and Microsoft publish seller-report and payout documentation for their own marketplaces; the applicable agreement and current portal data control a specific seller relationship.
- PCAOB evidence concepts inform traceability, but this research design is not an audit or assurance procedure.
- IRS and NIST sources inform record retention and access design but do not decide revenue, tax, principal-agent, or foreign-exchange accounting.
Build a traceable usage-to-cash bridge
Inventory seller reports, define identifier mappings and cutoff, and assign judgment and escalation before routine preparation.
Discuss a marketplace payout workflow