
The proposed study asks what reopened exceptions can reveal about evidence sufficiency and closure definitions? Reopening may expose weak evidence, an unclear closure rule, or a later source correction. The design therefore records context and exceptions instead of reducing the workflow to one performance score.
Bookkeeping Operations
Exception reopen rates after bookkeeping review
An evidence-led research framework for exception reopen rates, including measurement choices and limitations.
Published · 10 listed sources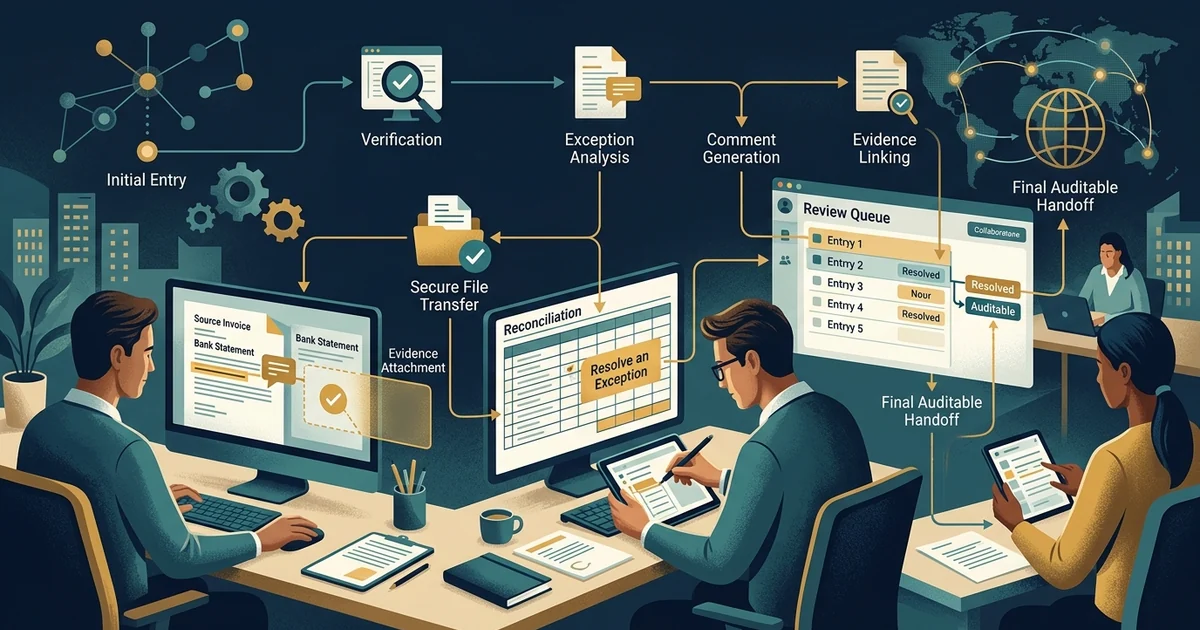
Key takeaways
- Define the observation and denominator before collection.
- Separate public-source principles from local operational inference.
- Treat the result as a prompt for review, not proof of accuracy.
The question worth measuring
What the public sources support
GAO and COSO describe responsibility, useful information, control activities, and monitoring. PCAOB and AICPA materials discuss the relevance and reliability of evidence; those concepts do not turn a bookkeeping study into an audit. NIST covers data integrity and role-based access. IRS recordkeeping guidance, FASB concepts, the IFRS Conceptual Framework, and SBA material provide additional context for financial records. None of these sources publishes a universal benchmark for exception reopen rates.
Define the observation first
Use one reviewable task, reconciliation, evidence packet, or exception with a known preparer and reviewer. Capture exception class, first closure, reviewer, reopening reason, response cycles, age, and final disposition. Record the entity, period, source system, complexity, and whether the work required an authorized judgment. Set inclusion and exclusion rules before looking at results.
A bounded study design
A future pilot could cover consecutive periods in one defined process. Save the raw extracts, minimize personal data, and apply written classifications. A second reviewer should retest a sample for consistent coding. Report the number of observations, missing fields, distributions, and outliers alongside any average. This article uses no private client dataset and reports no experimental finding.
Keep claims in their proper lane
The public sources support traceable records, clear responsibilities, access control, and reviewable evidence. Applying those principles to exception reopen rates is OffshoreBookkeepers.com operational analysis. Any claim that a process change improves an outcome is an inference until local data tests it.
Rules that make comparison possible
Write down how the clock starts and stops, what counts as complete, how reopened work is treated, and how missing data appears in the result. Freeze the denominator. Keep the first extract and every calculation version. Segment only when the groups have a practical meaning, such as system, task type, or evidence status.
Roles and safeguards
A bookkeeper can assemble authorized records, apply fixed labels, calculate descriptive measures, and log exceptions. The finance owner approves definitions and resulting actions. An independent reviewer tests whether the labels were used consistently. Legal, tax, payroll, audit, accounting-policy, and employee-performance conclusions remain with authorized professionals.
Read the result cautiously
Comparison does not establish cause. Staffing changes, new accounts, altered deadlines, system migrations, missing access, and unusual transaction volume can move the measure. Inspect the underlying observations before changing a process. Avoid ranking individuals when the study was designed to examine workflow conditions.
Test one small change
A team might clarify one intake field, preserve a report definition, assign a working backup, or tighten a closure label. Choose the change before the next observation period, state the expected signal, and keep other known process changes in the study notes. The result should prompt specific review questions, not an assurance claim.
Limits of this framework
The framework has not been validated on a representative sample. Definitions, privacy duties, software logs, staffing, and materiality differ across organizations. Small samples are unstable, missing fields may be systematic, and association cannot prove causation. Any local study should disclose those limits with its results.