Evidence & Quality

Review comment resolution in offshore bookkeeping: an evidence review

A source-based review of what makes remote bookkeeping review comments resolvable and auditable, including evidence, methodology, limitations, operating implications, and a bounded conclusion.

A source-based review of what makes remote bookkeeping review comments resolvable and auditable, including evidence, methodology, limitations, operating implications, and a bounded conclusion.

Key takeaways

  • A review comment should identify the questioned assertion and the exact evidence or decision requested.
  • Record the responder, reviewer, protected decision owner, disposition, and explicit closure evidence.
  • Interpret comment counts with workload, waiting owner, response cycles, and sampled records rather than as a standalone quality score.

Research question and scope

This review asks what information makes a bookkeeping review comment understandable, answerable, and closable when preparer and reviewer work at different times or locations. A comment is treated as a controlled question about a record, not as evidence of poor performance or as an approval by itself.

The scope covers the questioned assertion, requested evidence, response, decision owner, and closure state. It excludes independent accounting judgments, legal or tax advice, access administration, and any claim that remote work causes more review comments.

Evidence base

The four-source list combines audit-evidence and audit-documentation standards, an information-system audit-record control, and a specific federal corrective-action rule. These materials govern different contexts and are not merged into a new compliance requirement.

They are used to ask whether a comment record identifies the event, source, issue, performer, reviewer, timing, outcome, and responsible decision owner. The proposed comment fields are an operating design created for this article.

What the sources support

PCAOB AS 1105 addresses evidence relevance and reliability in an audit, while AS 1215 addresses documentation of procedures, evidence, conclusions, performers, reviewers, and dates. Used as bounded analogies, they suggest that attaching a file is not enough unless it answers the questioned assertion and remains reviewable.

NIST SP 800-53 AU-3 describes audit-record content such as event, time, source, outcome, and identity. For covered federal-award audits, 2 CFR 200.511(c) gives a concrete corrective-action example involving a responsible contact, planned action, and completion date. Neither source turns that example into a universal bookkeeping mandate.

Operational interpretation

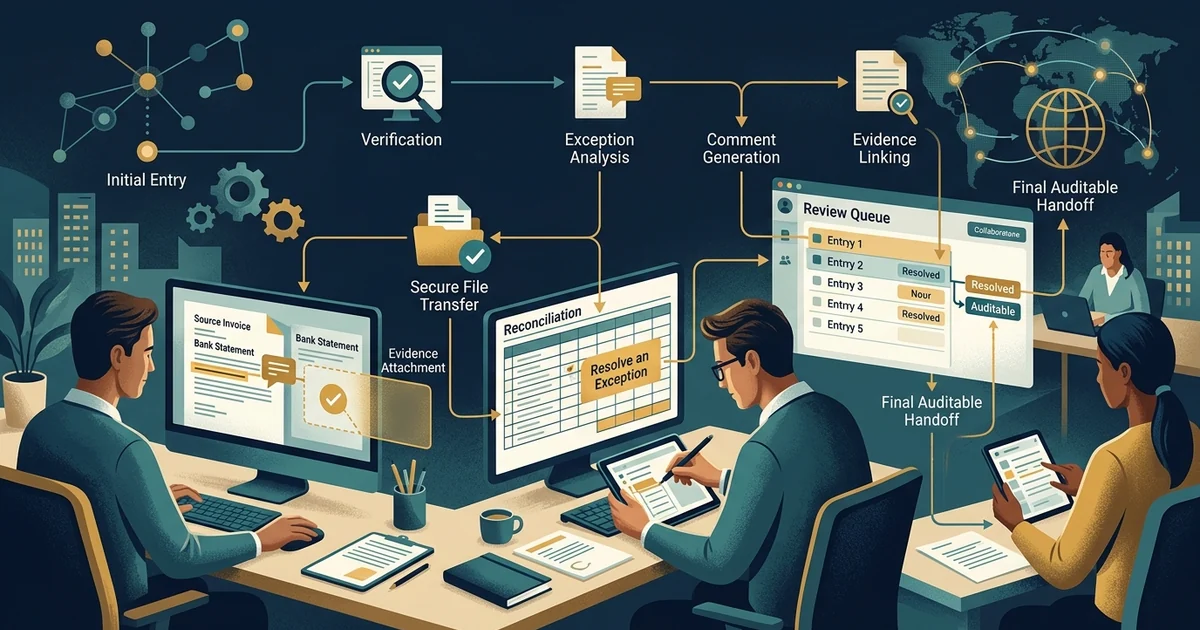
A review comment should name the account or work item, period, questioned assertion, evidence already examined, exact request, responder, reviewer, protected decision owner if needed, due point, response, disposition, and closure evidence. Statuses can distinguish open, awaiting evidence, awaiting owner decision, returned for correction, answered, and closed.

The reviewer, not the preparer alone, should close the comment. A response may resolve a factual gap, propose a correction, or identify that the issue requires controller or CPA judgment. The record should make those paths visible without implying that a response equals acceptance.

Evidence and measurement

Useful measures include open comments by stage, time waiting by owner, response cycles, reopen events, repeated question types, and comments closed without evidence. Counts need a workload denominator because more comments may reflect more records reviewed or a deliberately deeper review.

Sample comments from straightforward, corrected, disputed, reopened, and owner-decision groups. Check whether a new reviewer can identify the question, evidence, response, decision, and closure basis without reconstructing chat history. That test assesses documentation quality, not accounting correctness by itself.

Methodology

This article qualitatively mapped four listed public materials to a generic review-comment lifecycle. It compared fields relating to evidence fit, attributable documentation, audit-record content, and corrective-action ownership. No client comment log, interview set, platform export, or outcome study was analyzed.

The evidence map distinguishes source-grounded concepts from the proposed workflow. The page's publication and update dates are editorial metadata and should not be read as a guarantee that external sources remain available or unchanged.

Limitations

PCAOB standards address audits, NIST controls address information systems, and 2 CFR 200.511 applies to a defined federal-award audit context. Their presence does not make an ordinary bookkeeping review subject to those regimes.

The proposed fields have not been tested for every accounting platform, team size, or review policy. A business should adapt them to its obligations, materiality process, retention rules, and professional-advice relationships.

Implementation test

Create redacted or synthetic comments for a missing source, wrong period, unclear calculation, disputed mapping, access-limited action, and controller decision. Ask a preparer to respond and a separate reviewer to decide whether the record is answerable and closable under the written definition.

Record where participants disagree about the assertion, requested evidence, owner, or closure basis. Revise the template rather than granting broader authority. The exercise tests the clarity of local procedure, not whether the cited organizations approve the template.

Conclusion

Review comments are more traceable when they identify the questioned assertion, requested evidence, responder, decision owner, response, disposition, and explicit closure proof. This structure is an operational interpretation of listed concepts, not a finding that one template improves offshore bookkeeping outcomes.

Keep closure and protected decisions with authorized reviewers, test the fields on local examples, and monitor reopened comments for ambiguous instructions or incomplete evidence.

Source notes

The evidence map assigns AS 1105 to evidence fit, AS 1215 to attributable audit documentation, NIST AU-3 to event-record content, and 2 CFR 200.511(c) to a bounded corrective-action example. No source prescribes this bookkeeping comment template or demonstrates that it improves outcomes.

Evidence map

These notes connect bounded statements on this page to the listed public sources. They do not turn operational interpretations into empirical findings.

  1. PCAOB AS 1105 addresses the relevance and reliability of audit evidence and testing company-produced information for accuracy and completeness; it supplies an audit-context analogy for asking whether a response actually addresses the questioned assertion.
  2. PCAOB AS 1215 requires audit documentation to identify procedures, evidence, conclusions, performers, reviewers, and dates; it is the bounded source for proposed attribution and chronology fields in a comment record.
  3. NIST SP 800-53 control AU-3 specifies audit-record content including event type, time, location, source, outcome, and associated identity; that information-system model supports attributable status history but does not prescribe bookkeeping review comments.
  4. For covered federal-award audits, 2 CFR 200.511(c) requires corrective-action plans to include the responsible contact, planned action, and anticipated completion date; this is a bounded example for owner and due-point fields, not a rule for ordinary bookkeeping review.

Listed sources

  1. PCAOB, AS 1105: Audit Evidence
  2. PCAOB, AS 1215: Audit Documentation
  3. NIST, SP 800-53 Rev. 5 Update 1
  4. eCFR, 2 CFR 200.511: Audit findings follow-up

Related research