Bookkeeping Operations

Time-zone handoffs in offshore bookkeeping: evidence and operating implications

A source-based review of how time-zone boundaries affect bookkeeping handoffs and owner acceptance, including evidence, methodology, limitations, operating implications, and a bounded conclusion.

A source-based review of how time-zone boundaries affect bookkeeping handoffs and owner acceptance, including evidence, methodology, limitations, operating implications, and a bounded conclusion.

Key takeaways

  • Record both an absolute event time and the named zone relevant to the business cutoff.
  • Make transfer, acknowledgment, owner decision, acceptance, and escalation separate events rather than inferring acceptance from silence.
  • Measure waiting by stage and owner; cross-zone coverage alone does not establish shorter cycle time.

Research question and scope

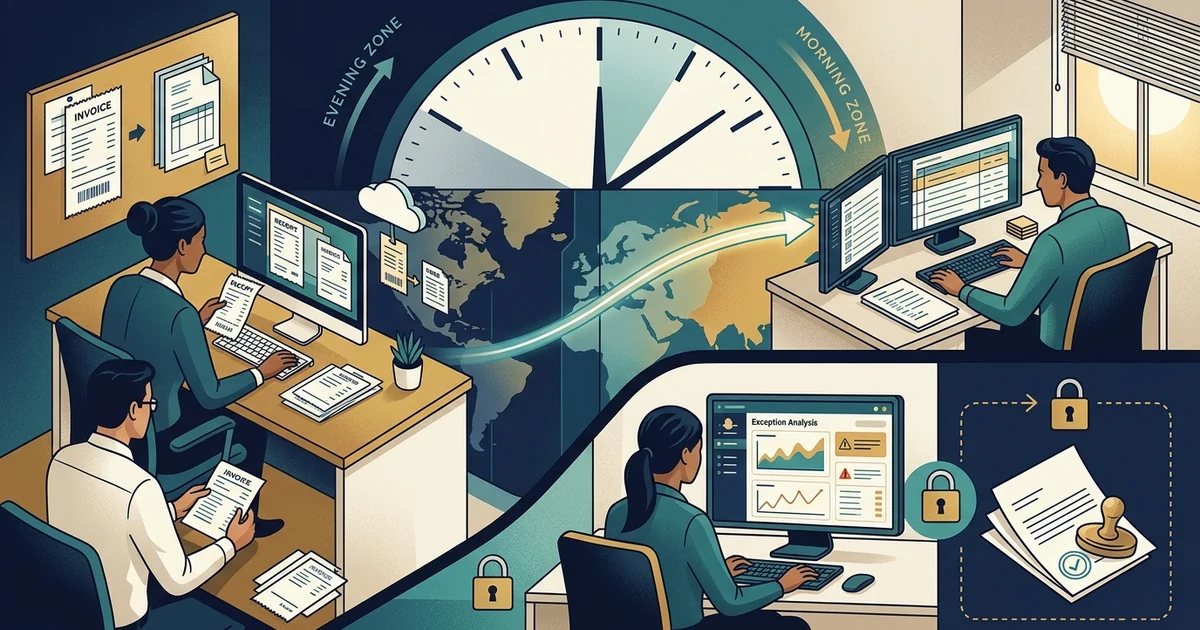
This review asks which timestamp and ownership fields make a bookkeeping handoff understandable when work crosses time zones. It does not assume that overnight coverage makes processing faster or that geographic separation causes delay. A handoff is examined as a transfer of a defined work state to a named receiver.

The scope includes event time, local cutoff context, source zone, preparer, receiving owner, acceptance, escalation, and review result. It excludes labor-law advice, service-level guarantees, and accounting judgments.

Evidence base

The listed materials cover internal control, access, records, audit documentation, information-system audit records, and internet time representation. They serve different purposes. NIST SP 800-53 and PCAOB AS 1215 are used only within their respective information-system and audit contexts; RFC 9557 and IANA materials address timestamp and time-zone representation rather than bookkeeping policy.

No source in the list measures offshore handoff performance. The proposed handoff receipt is therefore an operating interpretation that a business must test against its own close calendar and owner availability.

What the sources support

NIST SP 800-53 audit-record controls include concepts such as event, time, source, outcome, and identity. PCAOB AS 1215 separately discusses who performed and reviewed audit work and when. Those context-specific models support an attributable chronology but do not prescribe an ordinary bookkeeping schema.

RFC 9557 describes internet timestamps that can retain a numeric UTC offset and a named time zone, while IANA maintains time-zone data used to interpret civil time rules. These sources help prevent ambiguous timestamps. The business must still define which local cutoff matters and who may accept an exception.

Operational interpretation

A handoff receipt can record work item, covered period, source version, state at transfer, preparer, transfer timestamp with offset, named time zone when local context matters, receiving owner, expected decision, acceptance event, escalation point, and closure evidence. Store the absolute event time and the business-facing local cutoff rather than a bare clock time.

Preparation can continue across working hours, but acceptance should be explicit. A remote preparer should not infer approval from silence, move a protected cutoff, or act on an ambiguous local deadline. Those decisions remain with named client-side owners.

Evidence and measurement

Track elapsed time by stage and owner rather than combining all waiting into one duration. Useful events include prepared, transferred, acknowledged, returned, owner decision requested, accepted, and closed. Preserve the relevant zone and offset for any local cutoff comparison.

Report distributions and sampled records, including daylight-saving transitions, late arrivals, unacknowledged transfers, reopened items, and owner decisions. The observations can show where time accumulated but do not prove why it accumulated or that location caused the result.

Methodology

The article qualitatively mapped four listed public materials to a generic cross-zone bookkeeping handoff. It compared concepts for attributable event records, performer-reviewer chronology, internet timestamp representation, and named-zone interpretation. It used no production timestamps, interviews, vendor data, or controlled performance study.

The evidence map identifies the listed sources behind the central timestamp and ownership concepts. Publication and update dates are page metadata, not claims that all external resources were checked on that date.

Limitations

The cited sources do not define a bookkeeping service level, owner response time, or universal cutoff. RFC and IANA materials help represent time but cannot decide which zone governs a contract, filing, payroll, bank, or close process. NIST and PCAOB materials also have contexts that may not apply directly to the reader.

Calendar rules, holidays, daylight-saving changes, system clocks, client availability, and local obligations can affect a handoff. The business should document its governing cutoff and escalation path with appropriate advisers and system owners.

Implementation test

Test with synthetic or redacted handoffs that include two named zones, a daylight-saving transition, a late source file, an unacknowledged transfer, a protected owner decision, and a reopened review item. Ask two people to identify event order, governing cutoff, current owner, next action, and escalation time from the same record.

Investigate any disagreement about chronology or authority and revise the receipt fields. Do not use the exercise to reduce approval controls or promise a turnaround time. It tests whether the local handoff record is interpretable.

Conclusion

Cross-zone coverage can extend the hours in which preparation occurs, but it does not by itself prove shorter cycle time. A clear handoff records absolute event time, relevant named zone, work state, receiving owner, acceptance, escalation, and review result. This is a proposed operating design rather than an empirical outcome from the listed sources.

Businesses should test it across their actual cutoffs and retain explicit owner acceptance for protected decisions and exceptions.

Source notes

The evidence map assigns NIST AU-3 to event-record content, AS 1215 to audit-work chronology, RFC 9557 to offset-plus-zone timestamp representation, and IANA to civil-time rule data. None proves an offshore cycle-time benefit, prescribes a bookkeeping service level, or chooses the governing cutoff.

Evidence map

These notes connect bounded statements on this page to the listed public sources. They do not turn operational interpretations into empirical findings.

  1. NIST SP 800-53 control AU-3 specifies information-system audit-record content including event type, time, location, source, outcome, and associated identity; that model supports attributable handoff events but does not define bookkeeping acceptance.
  2. PCAOB AS 1215 requires audit documentation to identify who performed and reviewed work and the dates of that work and review; this audit-context chronology is used only as an analogy for named preparer and reviewer fields.
  3. RFC 9557 defines an internet timestamp format that can include a UTC offset plus a bracketed time-zone name and explains that offsets alone do not establish a time zone; it supports the proposed timestamp representation, not a cutoff policy.
  4. IANA maintains the Time Zone Database containing representative locations and civil-time change history; it supports named-zone interpretation but does not determine which zone governs a business event.

Listed sources

  1. NIST, SP 800-53 Rev. 5 Update 1
  2. PCAOB, AS 1215: Audit Documentation
  3. IETF, RFC 9557: Date and Time on the Internet
  4. IANA, Time Zone Database

Related research